
Five tickets. Five closed labels. One apartment entry door that has kept failing to latch. When should that record change an investor’s view of maintenance expense? When closure cannot be connected to a documented repair and appropriate verification. In this hypothetical review, the dashboard looks finished before the operating question is answered.
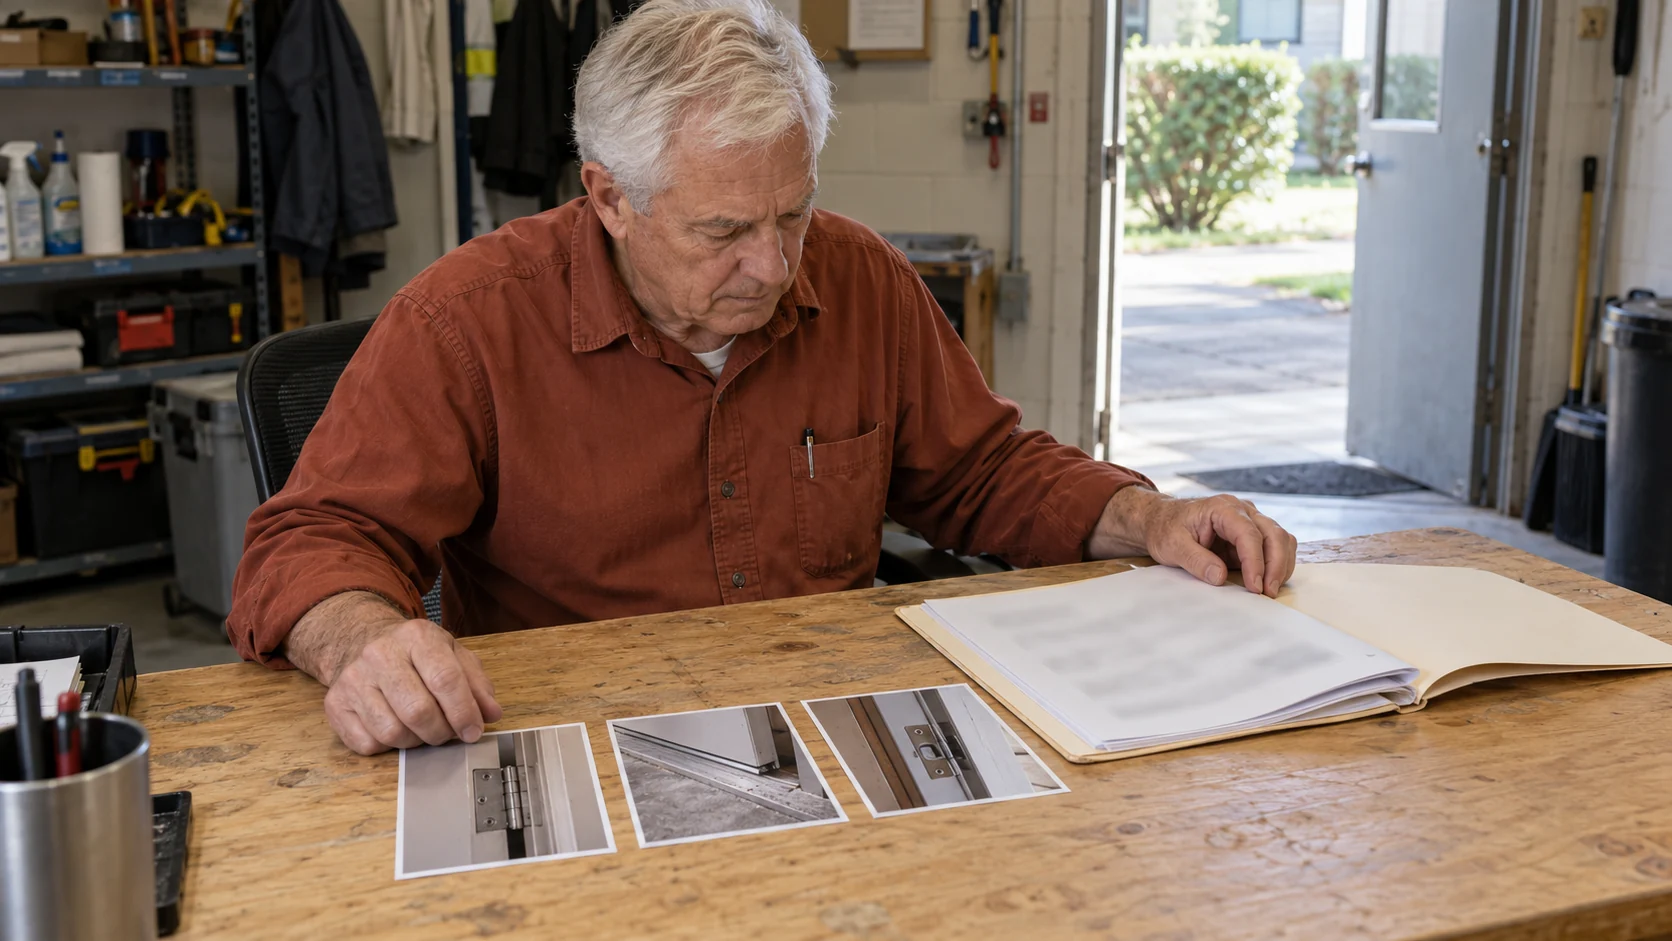
An accredited investor reviewing a Southern California apartment building sees a tidy maintenance summary. The recurring door issue is buried in the underlying notes, where a recommendation has no recorded disposition. This invented example follows the decision to reopen that history. It describes neither a VWC property nor a finding that a particular repair is required.
Reopening the history behind the green status
The investor requests the underlying export before accepting the summary. Closed, canceled, reopened and outstanding requests all matter: one closed door ticket may have become a new request with a new number. The acquisition team checks the export period, any management transition and whether phone or email complaints reached the same system.
Group potentially related records using three dimensions: the reported symptom, the precise location, and the sequence of dates. Preserve the original descriptions alongside any standardized categories. A change from “entry problem” to “hardware adjustment” should not automatically break the history of a recurring door complaint.
- Issue: What did the resident or staff member actually report, rather than what category was selected?
- Location: Which apartment, doorway, fixture, or common area was involved?
- Time: When was it reported, attended, closed, and reported again?
- Connection: Which earlier ticket, vendor visit, or recommendation does the new record reference?
These links are review leads, not technical findings. Similar complaints in neighboring apartments do not establish a shared building-system defect. A qualified professional must evaluate any suspected connection. The investor’s task is to identify where the explanation is incomplete, not to diagnose concealed conditions.
Separate administrative closure from a verified repair
Reading the door records changes what the word closed means. One entry may record attendance; another may remove a duplicate; another may document completed work. Ask management to explain those codes. The same status applied to different events cannot establish that every reported problem was resolved.
For each material recurring issue, assemble a short chronology containing the original request, attendance notes, work authorization, invoice, any recommendation for additional work, and the evidence used to close the issue. Record gaps explicitly. An invoice describing a service call establishes less than an invoice identifying the location, work performed, and relevant parts.
Verification should fit the work. A dated photograph may document replacement of visible hardware, while an intermittent complaint may require a documented functional check and follow-up. Resident confirmation can add context, but it does not replace technical verification where specialist judgment is necessary. Nor does silence after a visit prove that the condition disappeared.
Distinguish the date of the service from the invoice date, payment date, and ticket closure date. Otherwise, an accounting delay can look like a delayed repair, or prompt payment can be mistaken for prompt completion. Access limitations and unsuccessful visits should remain visible rather than being absorbed into a generic completion note.
Four visits and an unanswered recommendation
In the full hypothetical history, the five tickets span ten weeks and concern intermittent failure of the same common-entry door to latch. One entry duplicates another request. Four visits remain. The dashboard’s five completed items have become four service events and one continuing question.
Three visits generated invoices of $180, $240, and $180. The fourth was documented as a no-charge callback. A separate $60 credit against the final invoice reduced the total billed amount from $600 to $540. The ledger also shows $540, so the accounting reconciliation is complete.
The operating review is not. The first two invoices describe adjustments. The third visit note recommends additional work, but the file contains neither an authorization nor a documented decision about that recommendation. The callback note says the door operated during the visit, without addressing the outstanding recommendation or explaining how follow-up would occur.
At this point, accepting the dashboard would be easier than obtaining another assessment. The investor chooses to request the contractor’s evaluation, management’s decision on the recommendation and a verification record. That choice may add time and reveal more expense. It does not prejudge whether replacement is needed or whether a violation exists.
The reconciled $540 answers what was charged for the recorded visits. It cannot price the unresolved recommendation. Treating that total as the future repair budget would convert a complete accounting record into an unsupported condition judgment. The next scope, if one is needed, must be established and priced separately.
Test what the spending total leaves out
Once related tickets are grouped, reconcile their invoices to the ledger. Identify credits, warranty visits, unpaid invoices, and charges allocated across multiple locations. Avoid multiplying one invoice merely because several tickets reference it.
Also ask what the invoice total excludes. Employee labor may sit in payroll rather than the repair account. Materials may have been purchased in bulk. A pending recommendation may have generated no expense yet. Low recorded spending can therefore coexist with unresolved work, although that possibility needs evidence rather than assumption.
The broader review of property income and operating costs helps place these reconciled amounts in the operating statement. The narrower question here is whether the history supports carrying that repair expense forward as representative.
The sponsor’s next update should show three separate states for this issue: the $540 historical expense, any authorized work still incomplete, and the recommendation awaiting investigation. An interim response may be appropriate while parts or access are arranged. What the investor needs is an accountable next action, not another closed label.
If the investigation supports a larger project, connect its documented scope to the capital-expenditure plan and cash schedule. Do not assume every recurring request belongs in that plan, or remove recurring expense simply because a future project is proposed.
Why the same issue can disappear from a dashboard
Repeated requests can expose a process weakness as well as a property concern. The OCC’s Commercial Real Estate Lending handbook discusses operational risk from inadequate processes and the importance of reliable reporting and controls in bank lending. It does not prescribe apartment maintenance procedures; its relevant lesson is that a favorable summary is only as useful as the records and controls behind it.
The example also raises a reporting question: does management review recurrence, or only speed of closure? A team rewarded for clearing tickets can lose sight of a recurring condition even without intending to mislead. Ask how the door’s repeated appearances would reach a supervisor and what evidence would demonstrate lasting resolution.
- New ticket numbers repeatedly replace earlier requests without cross-references.
- Identical completion language appears despite different reported symptoms.
- Vendor recommendations have no recorded approval, rejection, or explanation.
- A software migration leaves older issues inaccessible or strips out attachments.
- A reporting period ends immediately after repairs, leaving little opportunity to observe recurrence.
Ticket volume alone is not a fair comparison between properties. More accessible reporting channels can produce more requests, while incomplete intake can produce fewer. Examine record coverage and the nature of the requests before interpreting a trend as improvement or deterioration.
Keep resident safety outside the budget debate
Not every repeat request has equal urgency. Reports involving access security, essential services, or other potential health and safety concerns deserve prompt review by the appropriate professionals, even while costs and responsibility remain under investigation.
The California Attorney General’s housing-conditions guidance for landlords and tenants describes habitability responsibilities and encourages tenants to document repair requests. That makes complaint correspondence relevant evidence alongside the maintenance platform. A closed ticket does not by itself establish compliance with applicable requirements.
Request appropriately redacted correspondence and inspection or enforcement records where relevant. Investors generally need the issue, timing, response, and disposition, not residents’ unrelated personal information. Qualified California counsel should assess property-specific obligations and local requirements; licensed technical professionals should address the condition and appropriate repair scope.
The condition for closing the investor review
Return to the door at the end of the review. A supported technical conclusion and documented follow-up could justify accepting the existing budget. A priced corrective scope could change it. An unexplained recommendation leaves the decision unfinished. The investor’s discipline is to keep that uncertainty visible while the appropriate professionals establish what comes next.
A documented repair may support the existing budget. An incomplete record may call for additional investigation before relying on that budget. A supported new scope may require revised expense or capital assumptions. If a material uncertainty remains unpriced or management cannot explain repeated closure without resolution, an investor can pause rather than treat missing evidence as a favorable outcome.
Maintenance histories belong alongside physical inspections and operating records in a complete acquisition review. Learn more about the VisionWise investment process.
Important information
Past performance is no guarantee of future results. All investments involve risk and may result in loss. This material is for informational purposes only and does not constitute an offer to sell securities or a solicitation of an offer to buy securities.