
For the tax rules referenced above, see IRS guidance on like-kind (1031) exchanges.
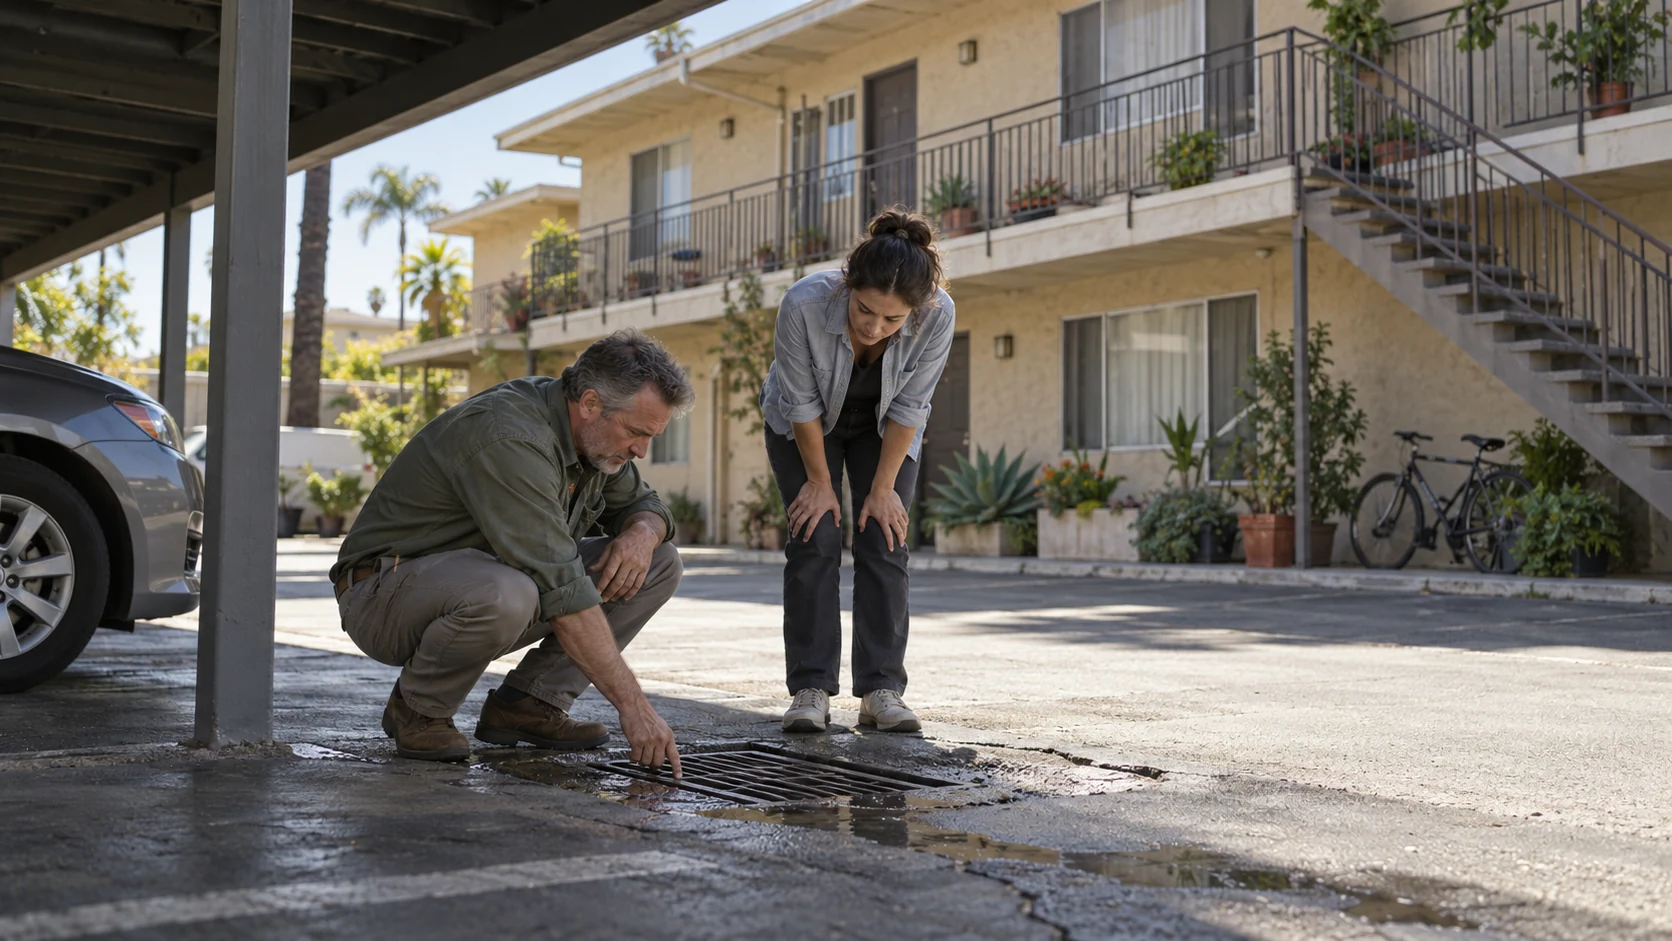
Drive the 405 from Irvine to Long Beach and look at what is beside the freeway. Almost none of it is new. The apartment buildings you pass were poured in the 1960s, 70s, and 80s, and most of them are full.
That view is the whole thesis. VisionWise Capital buys in coastal Southern California because the region has stopped building small apartment buildings, because the ones that exist are old and occupied, and because we can be standing in front of any of them within an hour.
Where Nobody Can Build the Competition
Real estate rewards scarcity, and coastal Southern California manufactures it in three ways. The first is geography: the ocean on one side and mountains and desert on the other leave a strip of buildable land that filled up decades ago. The second is zoning that, in most of Orange County and coastal Los Angeles, still favors single-family lots over anything with a shared hallway.
The third is the entitlement process itself. A developer proposing a 16-unit building on an infill lot in a coastal city faces design review, parking minimums, environmental review under the California Environmental Quality Act, neighbor hearings, and in the coastal zone a second layer of Coastal Commission oversight. The process is measured in years, and the carrying cost of those years is why so little small-scale multifamily gets built on the coast.
What does get built is large and expensive: 200-unit podium projects near transit, with rents set to recover land and construction costs that a 1974 building never paid. The new supply competes with itself at the top of the market. The eight-unit building two miles inland competes with nothing new at all, because nobody can make money building its replacement.
State law has begun to loosen this. Accessory dwelling units and density bonuses have added homes at the margins, and that trend deserves watching. But the fundamental arithmetic of coastal land, coastal politics, and coastal construction costs has not changed, and we do not underwrite as if it will.
The Building We Are Looking For
Our acquisition target has a name inside the firm: “Old, Tired and Occupied.” Each word is a filter.
Old means built roughly between 1970 and 2000, in a Class B neighbourhood, which in this market describes a great deal of housing that is structurally sound and cosmetically forty years behind. Stucco, a flat roof, a carport, galvanised plumbing, original kitchens. The bones are fine; the surfaces have been neglected.
Tired means the ownership has stopped investing. Typically the building is held by a family that bought it decades ago, has paid down the debt, and now collects rents well below what a renovated unit next door commands. Rents lag because raising them would mean spending on the units, and the owner has neither the appetite nor the capital. Under-capitalized, mismanaged, below-market rents, dated finishes, and a seller ready to move on: those are our five screens, and a tired building usually shows three or four.
Occupied is the word people skip, and it is the one that protects capital. A building with tenants in place has income on the day we close. We are not buying a lease-up story or a conversion; we are buying a rent roll that already exists and improving it unit by unit as tenants turn over, under California’s rent-increase rules rather than around them.
Size matters as much as condition. Five to fifty units is the range where a building is too large for the owner-occupier who lives in unit A and too small for the institutional buyer who needs a hundred doors to justify a site visit. It is a market of local families, estates, and 1031 exchangers, and it is priced accordingly. Our piece on why the eight-unit building is the sweet spot goes deeper on that middle ground.
Why We Insist on Being Able to Drive There
The firm exists because its founder, after years as a Registered Investment Advisor, could not find a real estate investment he could personally “go visit and kick.” That phrase is still how we underwrite.
A rent roll can be read from anywhere. What cannot be read from anywhere is whether the “renovated” units in the broker package are the two by the street or all twelve, whether the parking lot floods, whether the building next door is a well-kept fourplex or a problem, and whether tenants answer the door in a way that suggests they intend to stay. Our construction manager walks the roof and the crawl space before we bid. Our acquisitions team drives the block at 7 a.m. and again at 9 p.m., because a neighbourhood is two different places at those hours.
Proximity also governs what happens after closing. A renovation budget is only as good as the person checking the contractor’s invoice against the work, and that check happens in person, weekly, by someone who can get there without booking a flight. When a tenant reports a leak, the response time is measured in hours, and that responsiveness is a large part of why renovated units in our buildings re-lease at market rather than sitting empty.
Being local is also why we invite investors to do the same. Any accredited investor considering one of our offerings can ask to see a property, and when a tour can be arranged we will arrange it. If you cannot drive to the building and form your own view of the block, you are trusting a spreadsheet, and we would rather you trusted your eyes.
None of this makes a Southern California apartment building a certain outcome. Rents can flatten, insurance and property taxes reset on purchase, and a city can change its ordinance. What the focus gives us is a market we understand from the ground, an asset we can inspect, and a set of risks we have seen before. That is the reason the firm has never been tempted by a cheaper building in a city none of us has walked.
Want to see the kind of building we buy, in person? Talk to VisionWise Capital →
This content is for informational purposes only and does not constitute investment, legal, or tax advice. Real estate transactions and private placements involve significant risk, including potential loss of principal. Always consult qualified legal, financial, and tax professionals before making investment decisions.
For the tax rules referenced above, see IRS guidance on like-kind (1031) exchanges.