
Every way of owning apartments is a trade. You hand something over and you get something back, and the mistake most people make is only counting one side.
What follows is the ledger as I would draw it for a friend deciding between buying a building himself and putting the same money into a private real estate offering run by a sponsor. Four pairs, each with a debit and a credit, and then a note on who tends to land where.
Control, Paid for in Time
Own the building yourself and you decide everything: which property, which lender, which contractor, when the roof gets replaced, when to sell. Nobody can outvote you. If you have a strong view on a particular block or a particular renovation, direct ownership is the only way to act on it fully.
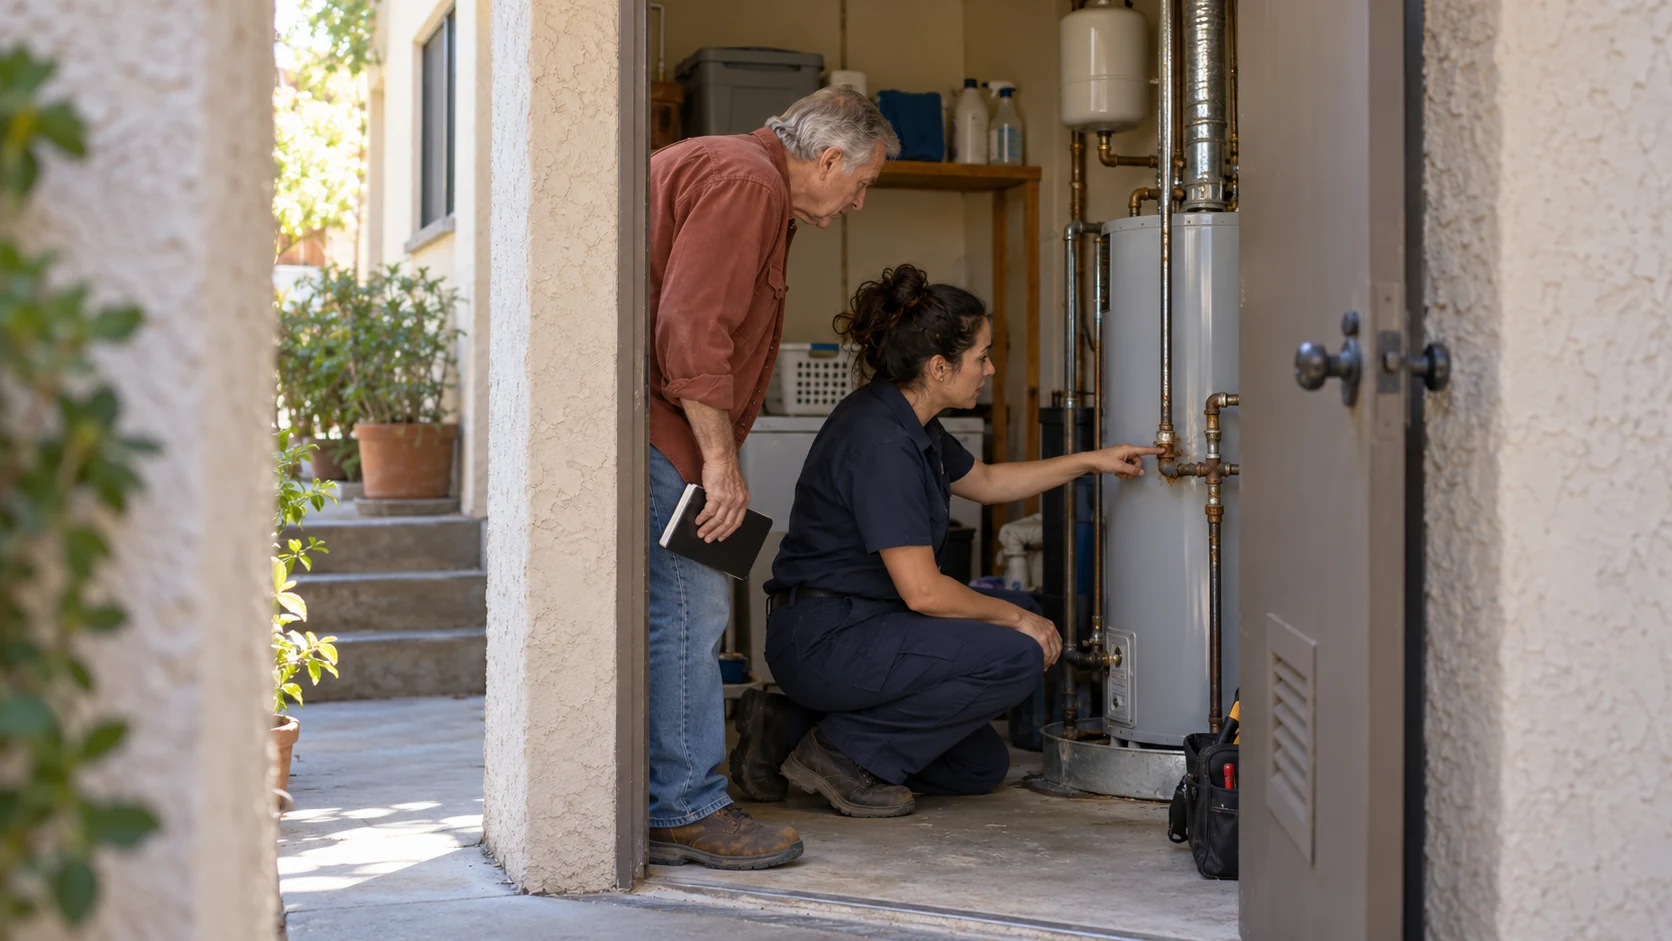
The bill for that arrives on a Tuesday night when a water heater fails in unit 7. A 12-unit building with a good third-party manager still needs its owner for perhaps five to ten hours in a quiet month and far more during a turnover, a refinance, or an insurance renewal. Delegating the tasks does not delegate the decisions.
In a sponsor-managed investment, the trade runs the other way. You give up the vote on operating decisions — the operating agreement reserves those to the manager — and you get your weekends back. What you keep is the decision that matters most: whether to commit to this sponsor, this plan, and these documents in the first place.
Upside, Paid for in Concentration
Buy a building outright and every dollar of improvement is yours. Push rents from $1,650 to $1,950 on eight renovated units and the extra $28,800 a year of net operating income belongs to no one else. There is no promote, no management fee to a sponsor, no split.
The cost is that every dollar of trouble is also yours, and it all sits in one address. A single building carries one roof, one soil report, one city’s rent ordinance, and one set of neighbors. For most individual buyers the equity in that building is a large share of their net worth, which means one bad year at one property moves the whole balance sheet.
A pooled offering dilutes both. The sponsor is compensated from the returns, so the investor’s share of a good outcome is smaller than an owner’s would be. In exchange, a $100,000 commitment can sit across several properties and several submarkets, and a problem at one of them is a line item rather than the whole story.
Information, Paid for in Effort
Nobody knows a building like the person who bought it. The direct owner has walked every unit, read every lease, and argued with the plumber. That first-hand knowledge is the reason experienced owners spot problems in a rent roll that a spreadsheet would miss.
It is also expensive to acquire. Learning to underwrite Southern California multifamily well takes years and a few mistakes, and the mistakes are made with real money. The owner who is still learning pays tuition in the form of an overpriced acquisition or an underbudgeted renovation.
The investor in a sponsor-managed offering trades that depth for a different job: judging the sponsor. You will never know the buildings the way the manager does, so you have to know the manager — track record, leverage policy, fee disclosure, how they report when things go wrong. The work is lighter, but it is not optional, and our checklist on how to vet a multifamily syndication sponsor is a reasonable place to start it.
Liquidity, Paid for in Simplicity
Here the ledger is less lopsided than people assume. Neither route is liquid. Selling an apartment building takes months of preparation, marketing, escrow, and lender coordination, and the price at the end depends on the market that month.
What the direct owner has is the right to start the clock. If you need out, you can list the building tomorrow and accept whatever the market offers. You can also refinance to pull equity without selling at all.
The investor in a private placement usually cannot start that clock. Transfer normally needs manager consent, there is rarely a buyer for a partial interest, and the exit happens when the business plan says it happens. The credit side is simplicity: one subscription, one Schedule K-1 (the partnership tax form that reports your share of income and deductions) each year, and a report every quarter instead of a bookkeeping habit you have to keep up yourself.
The Ledger on One Page
| You want | Direct ownership costs you | Sponsor-managed costs you |
|---|---|---|
| Control | Your time, on the building’s schedule | The vote on operating decisions |
| Upside | Concentration in one address | A share of returns to the sponsor |
| Information | Years of learning, paid in mistakes | Trust in someone else’s judgment |
| Liquidity | Months to sell, but you choose when | The right to choose the timing |
Who Tends to Choose Which
People who buy buildings directly usually share three things: local knowledge of a specific submarket, spare hours they are willing to spend on it, and a stomach for having most of their real estate wealth in one place. A retired contractor in Long Beach who wants a project is the type. So is the family that has owned the same fourplex since 1988 and understands it better than any appraiser.
People who choose a sponsor-managed offering are usually still working, or done working and unwilling to take on a second job. They want cash flow from a building they do not operate, they want it spread across more than one property, and they have decided that vetting a manager is a better use of their attention than vetting tenants. Many of them are accredited investors who came to real estate from a stock-and-bond portfolio and want something they can drive past.
Plenty of investors do both. They keep the building they know and put new money into an offering for the properties they would never have the time to run. That is not indecision; it is the ledger balancing itself.
VisionWise Capital sits on the sponsor-managed side of this table. We buy apartment buildings of five to fifty units across Southern California, keep loan-to-value under 50% on every property, and the founder — a former RIA — has skin in the game on every project. If you are weighing the two columns for your own situation, the fair comparison is our process against your own time and expertise, and the VisionWise Way lays that process out step by step.
Deciding between running a building and investing alongside someone who does? Talk to VisionWise Capital →
This content is for informational purposes only and does not constitute investment, legal, or tax advice. Real estate transactions and private placements involve significant risk, including potential loss of principal. Always consult qualified legal, financial, and tax professionals before making investment decisions.
Related Reading
- How a Private Multifamily Offering Differs From Buying a Rental Property
- The Role of the Sponsor in a Real Estate Deal
- How a Private Real Estate Offering Works: Structure and Roles
Explore VisionWise Capital
For independent investor education, see the SEC's investor.gov introduction to investing.