
How to Evaluate a Multifamily Investment Opportunity
The five pages an experienced reviewer reads first in a multifamily deal package, in order, and the three findings that end the review in the first hour.
The five pages an experienced reviewer reads first in a multifamily deal package, in order, and the three findings that end the review in the first hour.
Southern California apartment valuation starts with net operating income and a comparable market cap rate. The article examines submarket differences, rent-control exposure, vacancy assumptions, expense accuracy, and why rising income can accompany falling values.
Southern California apartment values in 2026 reflect interest rates, normalized rent growth, new supply, operating performance, and investor demand. Owners can update valuations by testing current NOI and relevant submarket evidence.
Rule 506(c) explained without the jargon: what Regulation D is for, how 506(b) and 506(c) differ, and what an advertised private offering actually tells you.
Off-market multifamily buyers usually need clear objectives, complete property records, verified income and expenses, financing details, legal information, and a process for documenting open questions with the owner.
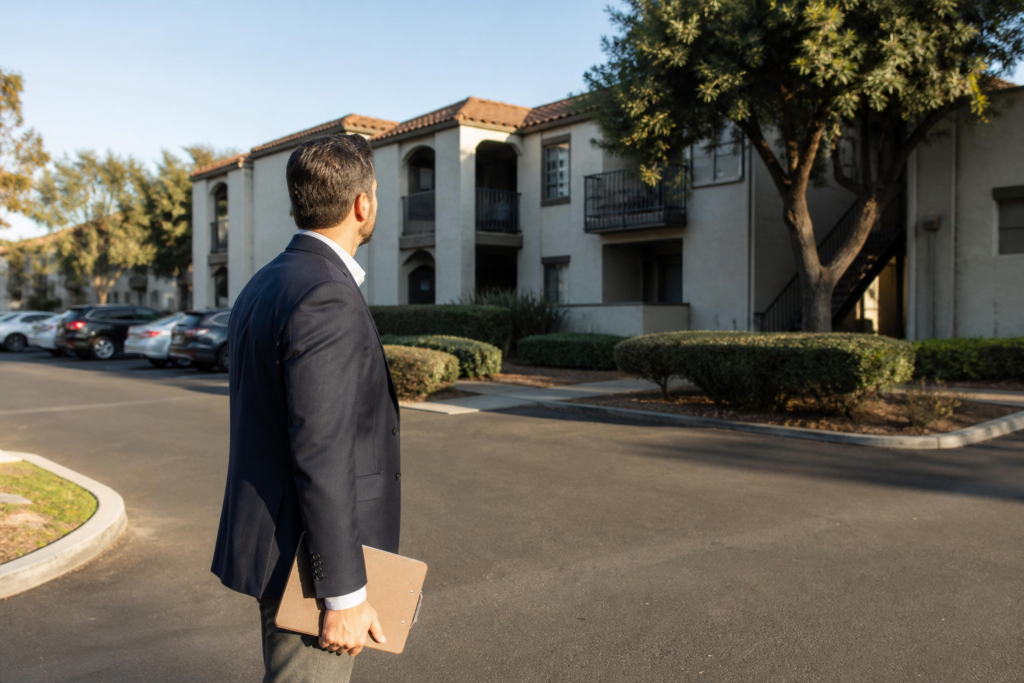
Orange County apartment valuation depends on NOI, loss-to-lease, debt coverage, local regulation, capital repairs, and comparable sales. The framework helps owners test generic cap-rate estimates against current submarket evidence.
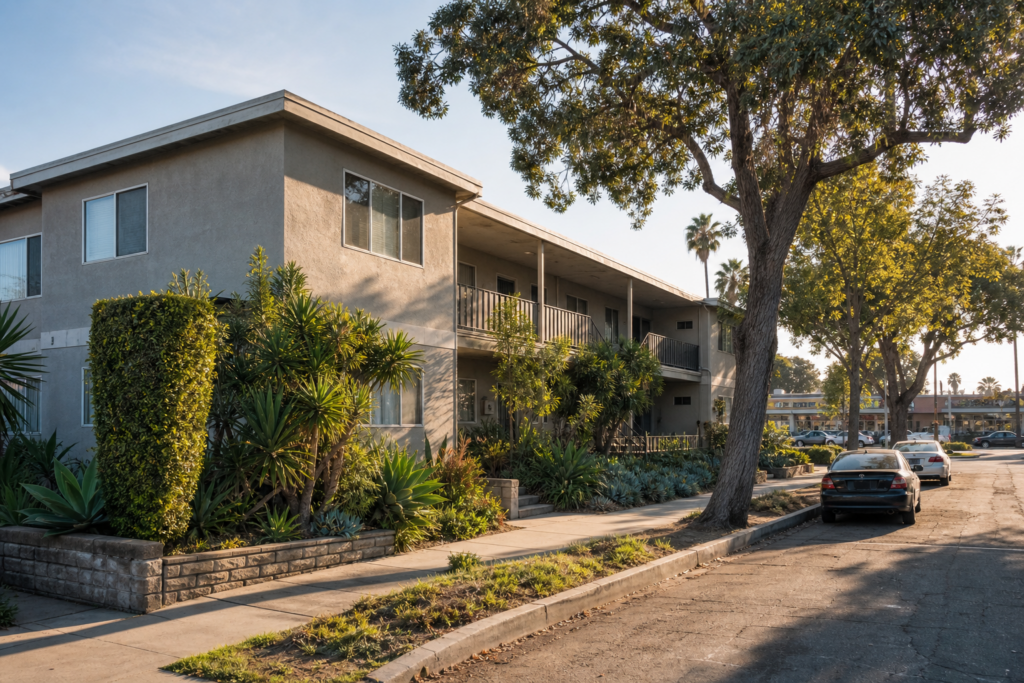
Evaluate apartment houses for sale in Southern California with a practical neighborhood and property due-diligence framework. Review rental demand, comparable properties, rent rolls, tenant protections, physical condition, operating expenses, capital needs, financing, and exit assumptions before relying on a pro forma. Use the field checklist to document evidence, stress-test projections, organize professional reviews, and compare opportunities consistently. This educational guide also explains why below-market rents are not automatic upside and why local market knowledge, inspections, legal review, and disciplined underwriting matter when assessing multifamily property risk and fit.
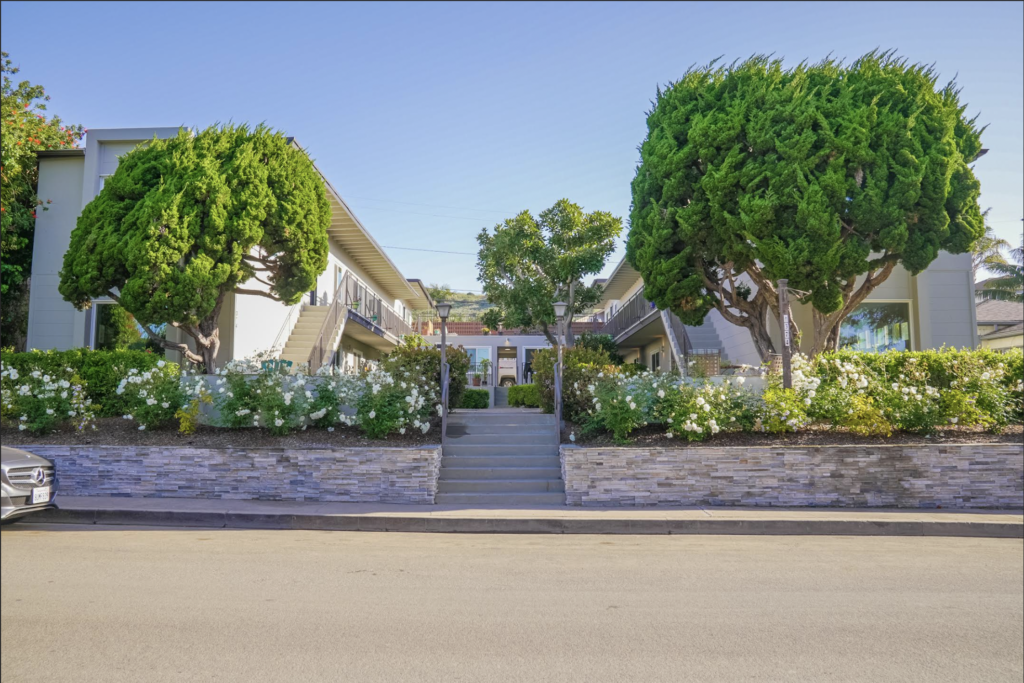
For RIAs and family offices: how leverage in an offering stacks with a client’s other debt, how to read a sponsor’s debt across all deals, and what to ask.

The seven parties in a private real estate offering, what each can and cannot decide, and who an investor actually calls when something happens.
The honest ledger of owning a building yourself versus investing through a sponsor: control, upside, information, liquidity, and who chooses which.