
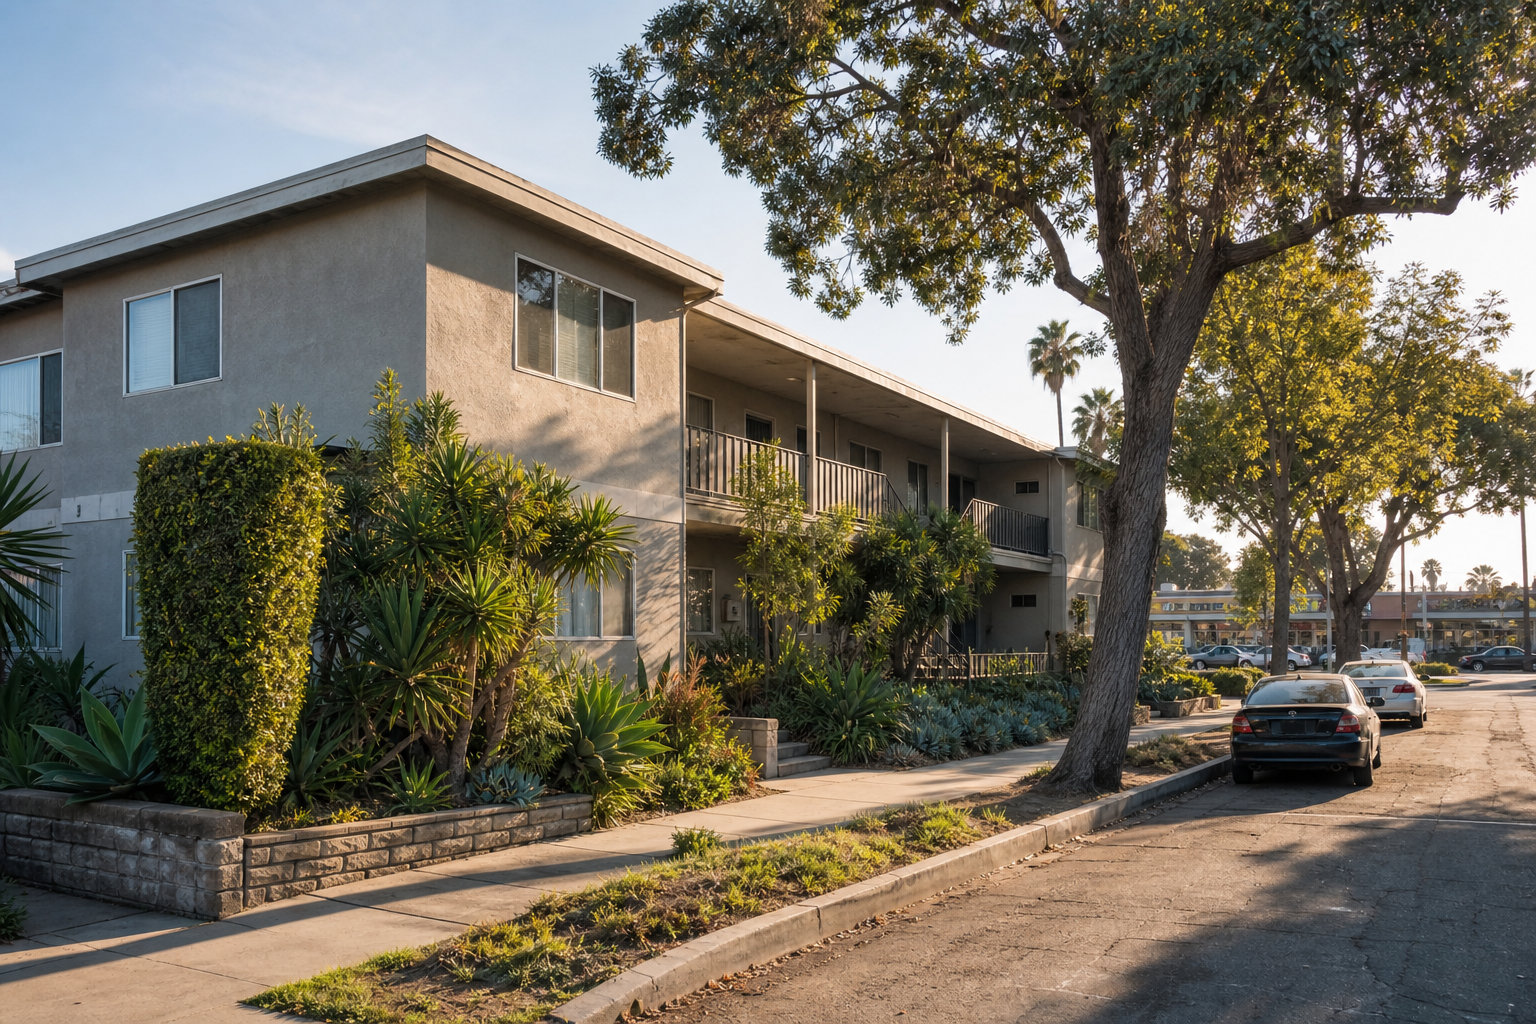
Most first-time buyers of a small apartment complex do not lose money on the building. They lose it on the five assumptions they brought to the building.
The 5–16 unit range in Southern California is where a lot of people make their first multifamily purchase, because the prices are reachable and the properties feel understandable. The same five mistakes show up again and again at that size. Each one has a specific check that prevents it, and none of the checks are expensive.
Mistake 1: Pricing a 1970 Building Like a 2010 Building
A great deal of the small multifamily stock in Orange County and Los Angeles was built between 1955 and 1979. Buyers see fresh paint and new appliances and price the building on its surfaces. The systems behind those surfaces are original, and they are what the next ten years of ownership will be spent replacing.
It happens because a residential inspection, the kind you had on your house, is not built to find it. A general inspector notes the water heater’s age; a contractor tells you the building still has galvanized steel supply lines, a cast-iron drain stack, a Zinsco or Federal Pacific electrical panel, and a flat roof that has been coated over three times instead of replaced.
The check: hire a licensed general contractor to walk the building and write a ten-year capital schedule with a cost for each item, and camera the main sewer line, which costs a few hundred dollars. As an illustration, on an eight-unit 1968 building it would not be unusual for that schedule to total $150,000 to $250,000. Whatever it totals, it comes off the price you can pay or goes into the reserve you must raise, and either way it belongs in the underwriting before you write an offer.
Mistake 2: Paying for the Seller’s Forecast
The marketing package for a small building often leads with what the rents could be. First-time buyers, who have usually been told the property has “upside”, accept that figure as the starting point and negotiate down from it.
It happens because the upside is genuinely there in many older buildings, and it feels reasonable to pay something for it. The problem is that you are paying for it before you have done the work, and in a rent-regulated market the timing of that work is not yours to set.
The check: build your own net operating income from the trailing twelve months of actual statements, with property taxes reset to your purchase price, since in California the assessed value resets at sale, and insurance at a fresh quote rather than the seller’s old premium. Then value the building on that figure. Illustrative numbers for a six-unit property: in-place NOI of $78,000 against a package figure of $98,000. At a 5% cap rate that is $1.56 million versus $1.96 million. The $400,000 difference is what the seller is asking you to pay for a renovation you have not started. Our guide to reading a multifamily rent roll shows where the in-place figure comes from.
Mistake 3: Closing With Nothing Left Over
Buyers stretch to the down payment and closing costs, take title with a few thousand dollars in the operating account, and meet their first vacancy and their first plumbing failure in the same month.
It happens because the reserve is the easiest number to cut when the deal is slightly out of reach. Nobody at the closing table asks about it, and the lender’s requirement, if there is one, is usually a minimum rather than a sensible amount.
The check: close with a cash reserve equal to six months of debt service plus the first year of the contractor’s capital schedule from Mistake 1, held in a separate account you do not touch for anything else. On an eight-unit building with a $7,500 monthly mortgage payment and $40,000 of first-year capital work, that is $85,000 sitting idle on day one. It feels excessive until the month it is not.
Mistake 4: A Floating Rate With No Cushion
A variable-rate loan often carries a lower starting rate than a fixed one, and on a thin deal that difference is what makes the numbers work. Buyers take it, and the numbers work until the rate moves.
It happens because rates feel abstract on the day you sign. They are not. Between March 2022 and July 2023 the Federal Reserve raised its policy rate by more than five percentage points, and an owner whose loan repriced with it watched a building that covered its payment comfortably stop covering it at all.
The check: re-run the debt-service coverage ratio (DSCR), which is NOI divided by annual loan payments, at the current rate plus two full percentage points. If it drops below 1.20, you cannot afford the floating loan, whatever it costs today. Prefer a fixed rate for at least the length of your renovation plan, or buy a rate cap and count its cost as part of the debt. The trade-offs are set out in fixed-rate vs. floating-rate real estate loans.
Mistake 5: Managing It Yourself From Forty Miles Away
The underwriting on a small building often only works if the owner manages it personally, so the buyer decides to do that, from a home an hour’s drive away and a job that takes the daytime hours.
It happens because the management fee looks like pure savings, and because the buyer imagines management as collecting rent rather than as showing a unit on a Tuesday afternoon, meeting the plumber at 7 a.m., and serving a notice correctly under a city ordinance they have not read.
The check: put a full third-party management fee in the underwriting from day one, whether or not you intend to use one. On small Southern California buildings that is generally a percentage of collected rent in the high single digits, plus a leasing fee per turnover. If the deal only pencils without it, the deal does not pencil; you have priced your own labor at zero and called it a return. If you live more than about thirty minutes from the building or work full time, plan to use the manager rather than merely to budget for one.
When a Sponsored Offering Is the Better Fit
Every one of these mistakes has the same root: a small building is an operating business, and the buyer wanted an asset. If what you want is exposure to Southern California apartments, the cash flow and the tax treatment, without the contractor walks and the 7 a.m. plumber, a private real estate offering run by an experienced sponsor is designed for precisely that. The sponsor buys the “Old, Tired and Occupied” building, carries the renovation, keeps the loan conservative, and reports to you quarterly; you read the report and receive a Schedule K-1 at tax time. Those offerings are open to accredited investors, and how a private multifamily offering differs from buying a rental property sets out the trade-offs honestly, including the illiquidity you accept in exchange.
Weighing your first small apartment purchase against a sponsored offering? Talk to VisionWise Capital →
This content is for informational purposes only and does not constitute investment, legal, or tax advice. Real estate transactions and private placements involve significant risk, including potential loss of principal. Always consult qualified legal, financial, and tax professionals before making investment decisions.
Related Reading
- Multifamily Capital-Expenditure Due Diligence
- Debt-Service Coverage in Multifamily Investing
- 8-Unit Apartment Buildings for Sale: The Sweet Spot of Southern California Multifamily
Explore VisionWise Capital
For independent investor education, see the SEC's investor.gov introduction to investing.